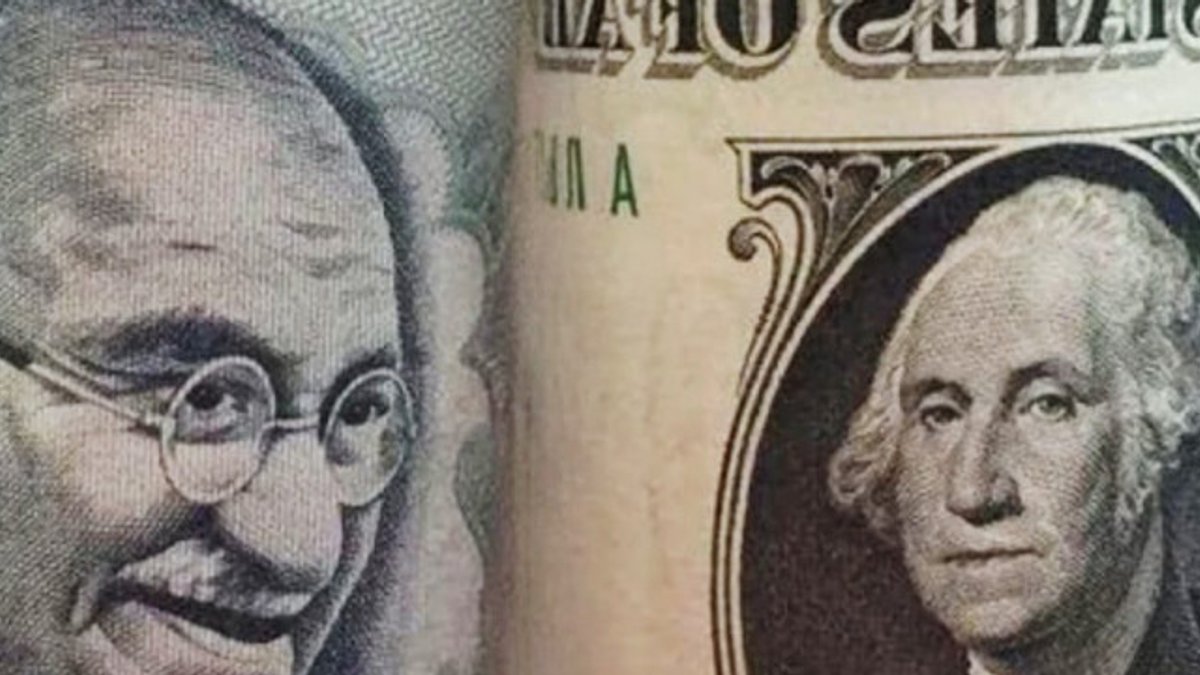
A rising stock market does not automatically indicate that people are becoming richer. When a currency loses value quickly, share prices can climb because more currency units are needed to purchase the same assets. The number displayed on the screen rises, yet the purchasing power of what it represents falls.
This distinction matters now because the West is undergoing one of the most severe bond bear markets in recent memory. In the United States, the year 2022 recorded the worst twelve-month performance for core bonds on record. European and British bonds have faced intense pressure since then, with several indices slipping to levels not seen for decades amid inflation spikes and fiscal concerns.
The Impact of Currency Fluctuations
Some analysts trace the turning point to August 2021, linking it to the United States’ withdrawal from Afghanistan. A second inflection point is identified as Russia’s invasion of Ukraine in February 2022. Their view holds that when Western powers lose influence over overseas economic flows, their banks absorb larger losses. Central banks then inject fresh liquidity, and much of that money finds its way into equities.
This reasoning helps explain the near-vertical rise of the Nasdaq and the S-plus 500. From that perspective, Europe, Britain, and Japan appear most vulnerable to a severe currency crisis. The United States faces a serious decline.
History provides stark warnings. In Weimar Germany in 1923, Zimbabwe in 2008, and Venezuela in the late 2010s, stock markets surged in local-currency terms while investors’ real wealth was devastated. The arithmetic is harsh: a portfolio that doubles while the currency loses ninety-five percent of its purchasing power leaves its owner roughly ninety percent poorer.
FCNR(B) Deposits and Currency Risk
FCNR(B) deposits are intended to shield investors from a fall in the rupee against the chosen foreign currency. In a U.S.-dollar deposit, both principal and interest remain denominated in dollars and are repaid in dollars. However, this structure does not address the risk that the dollar itself may lose value. If the dollar’s purchasing power declines by more than six percent over the same period, the real return becomes zero or negative.
Read Also: Tata Sons Weighs 25000 Crore Stake Buyout to Stay Private
The reserve-currency status of the dollar is under strain. Iran is seeking to make passage through the Strait of Hormuz conditional on payment in currencies other than the dollar. Russia and China stand to benefit from such a shift, which could erode the petrodollar system. This is a key point for non-resident Indians considering an FCNR(B) deposit, as the instrument’s sole function is to protect against a rupee decline relative to the selected currency.
For the FCNR(B) depositor, two linked risks emerge. First, the deposit may lose real value if the dollar weakens. Second, the investor forfeits any upside from a strengthening rupee against the dollar. J.P. Morgan has voiced a similar view, suggesting that de-dollarisation could lead to broad dollar weakness, softer returns on U.S. assets, and higher yields as countries diversify their reserves.
The concern is not only whether the dollars will be returned, but also what those dollars will purchase at the time of repayment. If one expects the dollar to remain broadly steady, the FCNR(B) product performs exactly as designed. Conversely, if one anticipates a material shrinkage in the dollar’s global role, a three-to-five-year dollar-denominated deposit does not constitute a safe haven.
Non-bank financial institutions, such as hedge funds, pension funds, and insurers, hold well over $200 trillion in assets, significantly exceeding the value of the entire gold market. This disparity in scale shows the potential for substantial price movements in precious metals if a fraction of these assets shifts into this market. Furthermore, the impact of dollar risk is exemplified by the fact that a portfolio doubling in value while the currency loses 95% of its purchasing power leaves the owner about 90% poorer, highlighting the importance of considering the real value of returns rather than just nominal gains.
The dollar’s reserve-currency status and its potential erosion have significant implications for investors. For instance, if the dollar loses more than 6% of its purchasing power over a given period, the real return on a dollar-denominated investment, such as an FCNR(B) deposit, could be zero or negative, even if the nominal return is positive.
This risk is particularly pertinent for non-resident Indians considering FCNR(B) deposits, as the instrument is designed to protect against rupee decline but does not address dollar risk. In the context of a potential shift away from the dollar, with countries like Iran seeking to make energy trade settlements in currencies other than the dollar, the importance of diversifying exposure and considering the real purchasing power of investments becomes increasingly clear.